Letter of Non-Crystallisation: A Layman’s Guide
Letter of Non-Crystallisation: A Layman’s Guide
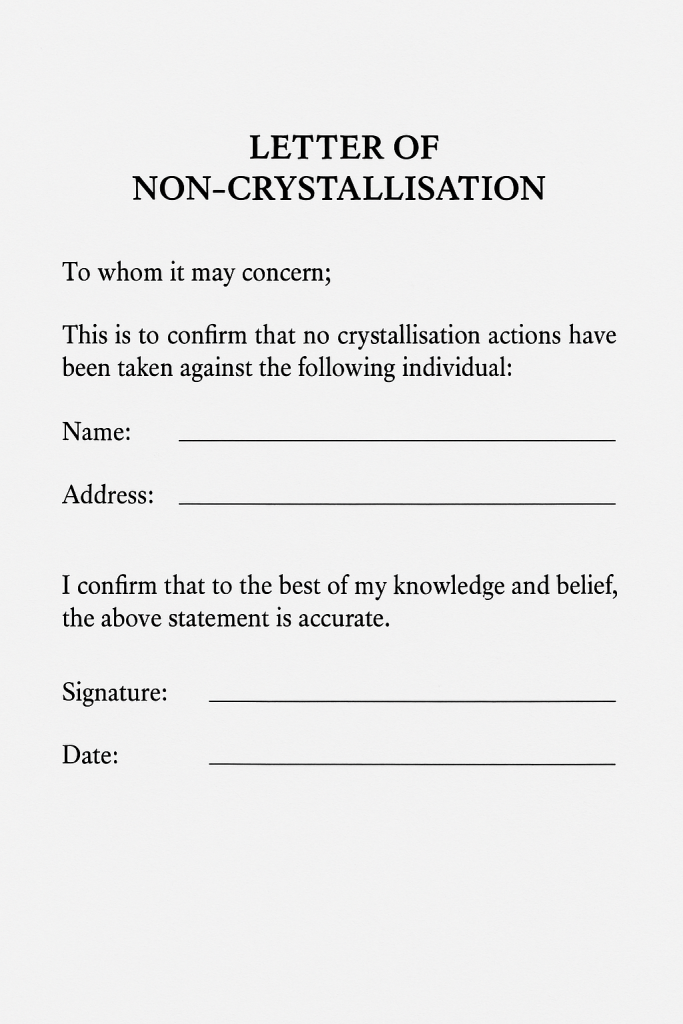
A letter of non-crystallisation is a simple document from a lender confirming that a “floating charge” over certain assets has not yet turned into a fixed charge. In everyday terms, it’s like a green light from your bank saying they haven’t locked up those assets, so you’re free to sell or deal with them as usual.
Why you might need one
- You’re buying assets (like equipment or property) that might be subject to a floating charge, and you need reassurance the seller can legally transfer them.
- You’re selling assets and need proof to a buyer or new lender that the assets aren’t frozen by an earlier loan.
- You’re restructuring or refinancing and need confirmation that existing floating charges remain “live” (i.e., not enforceable).
What it confirms
- The floating charge in question has not crystallised.
- The lender has not taken any steps to crystallise the charge.
- The lender consents to the sale (or to the creation of a second floating charge) over the assets, if applicable.
How floating charge crystallisation works
A floating charge “floats” over a changing pool of assets—like stock or cash—letting a company use them day-to-day. If certain events occur (for example, loan default or insolvency), the floating charge “crystallises,” automatically becoming a fixed charge. At that point, the lender can prevent any further dealings with those assets and may appoint a receiver or sell them to recover the debt.